
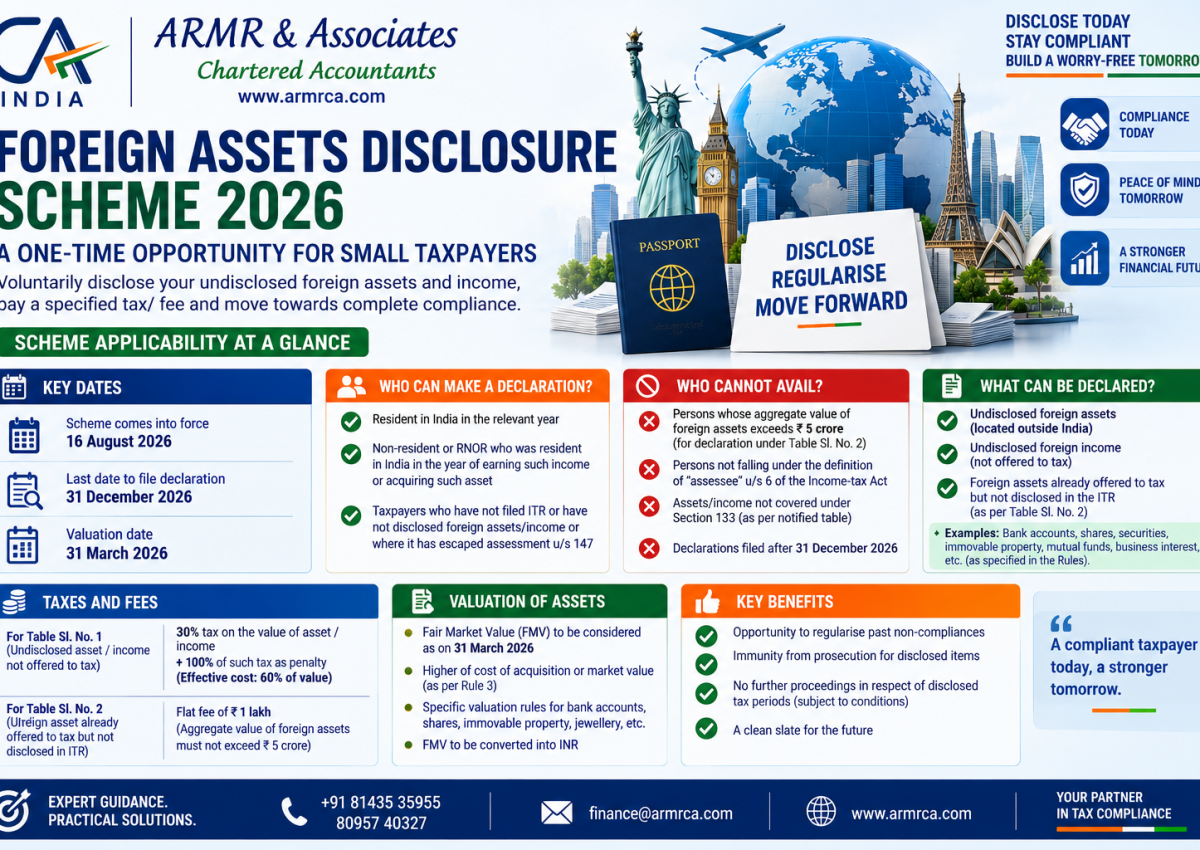
The Government of India has introduced the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FADS 2026) to provide eligible taxpayers with a one-time opportunity to regularise certain foreign assets and foreign income that were not appropriately disclosed in their Income Tax Returns.
The Scheme is particularly relevant for taxpayers having foreign bank accounts, shares, ESOPs/RSUs, overseas investments or immovable properties, especially where the underlying income was already disclosed and taxed in India but the foreign asset was inadvertently not reported.
Who Can Benefit from FADS 2026?
The Scheme broadly covers eligible taxpayers having:
- Undisclosed foreign assets or foreign income up to an aggregate value of ₹1 crore; or
- Specified foreign assets up to ₹5 crore, where such assets were acquired from income already offered to tax in India or from income earned while the taxpayer was a Non-Resident, but were not disclosed in the relevant return.
The applicability of the Scheme depends on the taxpayer’s residential status, source of funds, year of acquisition and previous tax compliance.
Foreign RSUs/ESOPs – An Important Case
Foreign RSUs and ESOPs are increasingly common among employees of multinational companies.
At the time of vesting, the value of RSUs may already have been:
- Included as a taxable salary perquisite;
- Reported in Form 16;
- Subjected to TDS; and
- Included in the employee’s Income Tax Return.
However, the resulting foreign shares may have been inadvertently omitted from Schedule FA.
Such a case should not automatically be treated as undisclosed foreign income. Where the underlying income used to acquire the asset has already been offered to tax, the taxpayer may fall under the specific ₹1 lakh fee category of FADS 2026, subject to fulfilment of the prescribed conditions and the ₹5 crore threshold.
Illustration
If an employee received foreign RSUs worth ₹25 lakh, and the entire ₹25 lakh was already taxed as salary, but the shares were not reported in Schedule FA, the taxpayer should examine whether the omission qualifies under the ₹1 lakh fee category rather than treating ₹25 lakh as undisclosed income.
Are NRIs Required to Disclose Foreign Assets?
Generally, no.
A taxpayer who is Non-Resident (NR) or Resident but Not Ordinarily Resident (RNOR) is generally not required to furnish Schedule FA for that assessment year.
Therefore, merely holding foreign assets while being an NRI does not, by itself, create a Schedule FA reporting obligation in India for that year.
However, an NRI/RNOR may still be relevant for FADS 2026 depending upon the year in which the foreign asset was acquired and the circumstances under which it was acquired.
Accordingly, residential status must be examined year-wise, particularly where a taxpayer has returned to India and subsequently became Resident and Ordinarily Resident (ROR).
Tax and Fee under FADS 2026
FADS 2026 provides two broad categories:
| Particulars | Undisclosed Foreign Asset/Income | Specified Foreign Asset |
|---|---|---|
| Threshold | ₹1 crore | ₹5 crore |
| Amount payable | 30% tax + additional amount equal to 100% of tax | ₹1 lakh fee |
| Relevant valuation date | 31 March 2026 | 31 March 2026 |
The ₹1 lakh category is particularly relevant where the foreign asset was acquired from income already offered to tax in India or during the period when the taxpayer was Non-Resident, but the asset was not disclosed in the relevant return.
Same Asset Omitted for Multiple Years
Where the same foreign asset was not disclosed for more than one year, the CBDT’s FAQ clarifies that the ₹1 lakh fee is payable only once for the first year of non-disclosure, subject to the conditions of the Scheme.
Therefore, taxpayers should identify the first year in which the asset became reportable rather than automatically treating every subsequent year as a separate default.
What About ITR-U?
An Updated Return under section 139(8A) may be available for correcting certain earlier-year omissions, subject to the statutory conditions and restrictions.
However, where the issue relates only to omission of a foreign asset from Schedule FA and the underlying income has already been taxed, taxpayers should compare the ITR-U route with FADS 2026 before taking corrective action.
A year-wise review should be undertaken covering:
Residential Status → RSU Vesting → Perquisite Taxed → Foreign Shares Held → Schedule FA → Dividend/Capital Gain → Corrective Action
What Should Taxpayers Do?
Taxpayers having foreign assets should:
- Determine their residential status for each relevant year.
- Identify all foreign assets and investments.
- Establish the source of funds.
- Verify whether the underlying income was already offered to tax.
- Review previous Income Tax Returns and Schedule FA.
- Check foreign dividends and capital gains, if any.
- Evaluate eligibility under FADS 2026.
- Separately examine any FEMA implications.
Conclusion
FADS 2026 provides an important opportunity for eligible taxpayers to regularise historical foreign asset reporting issues.
Particular care should be taken in cases involving foreign RSUs/ESOPs, where the underlying perquisite may already have been fully taxed as salary but the foreign shares were not reported in Schedule FA.
Similarly, NRIs should not automatically be treated as having failed to disclose foreign assets, as Schedule FA is generally not applicable to NR/RNOR taxpayers for those years.
Taxpayers should therefore undertake a year-wise review of residential status, source of funds, taxation and Schedule FA reporting before deciding whether FADS 2026, ITR-U or any other corrective action is required.
FADS 2026 is a one-time opportunity, and eligible taxpayers should evaluate their position before the prescribed deadline of 31 December 2026.
Disclaimer
This article is for general information purposes only and does not constitute professional advice. The applicability of FADS 2026 depends on the facts and circumstances of each taxpayer and the applicable provisions, rules, notifications and CBDT clarifications. Professional advice should be obtained before making any declaration under the Scheme.
© ARMR & Associates, Chartered Accountants
